Busy Is a Schedule, Not a Margin: Inside a 40-Job Month
May 1, 2026
Forty jobs a month. Revenue $2.4M and climbing. An accountant who said the business was profitable. And a bank account overdrawn twice in one quarter — both times covered quietly out of personal savings.
“I’m not losing money,” she told me. “The P&L says I’m making money. So where is it going?” Let me walk her month the way I walked it — because in a company this busy, the money doesn’t leave in one place. It leaves in four.
Leak One: Prices Borrowed from Competitors
Her actual cost on a standard residential remediation was $11.40 per square foot. She was pricing some jobs at $15 and some at $22 with no consistent logic — sharper on price where she wanted volume. Blended, she ran 29% gross margin. She believed she was running 38%. Pricing from what the competitor charges, instead of from what the work costs, doesn’t feel like a leak. It feels like being competitive.
Leak Two: Containment, Estimated at Half Its Cost
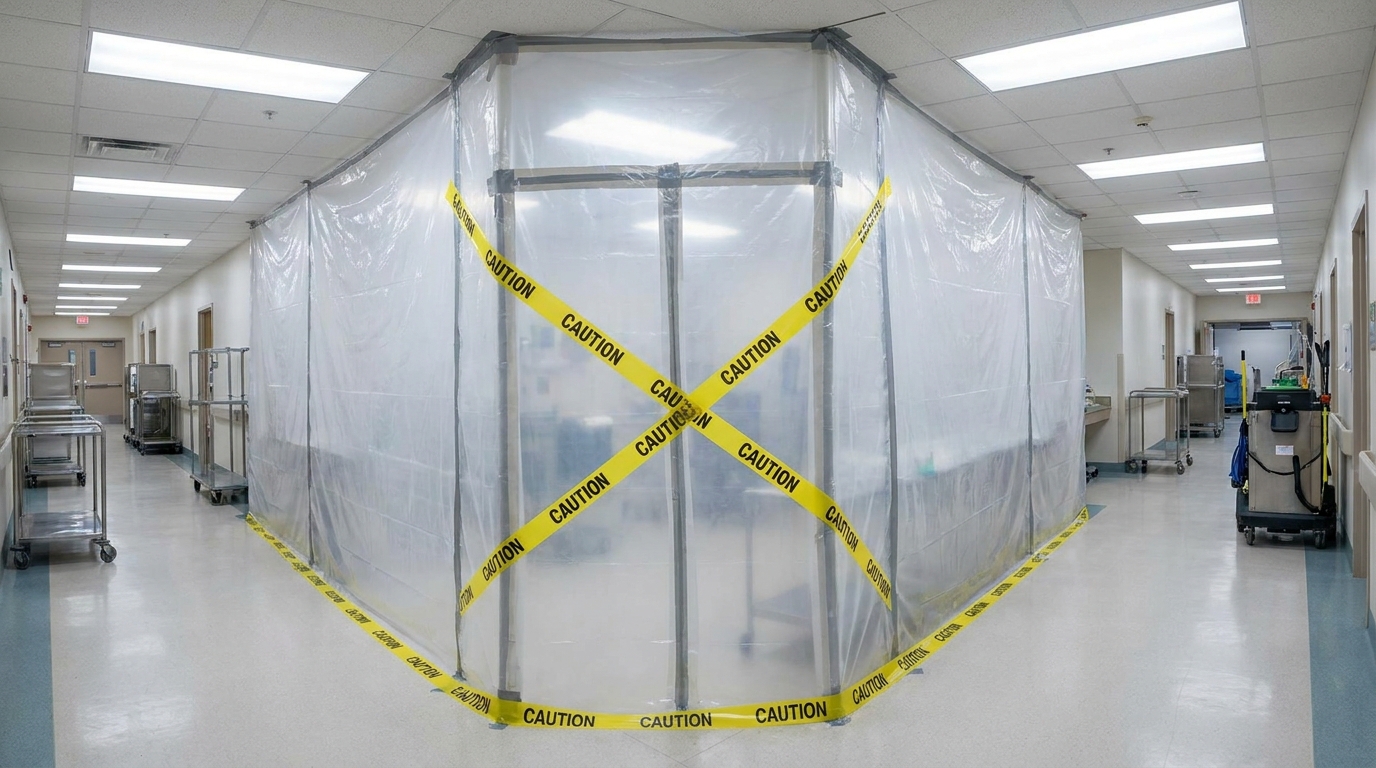
Her technicians spent 4–6 labor hours on containment setup and breakdown per job. Her estimates allowed 2. Containment materials ran 40% below actual on complex jobs. At 40 jobs a month, that one estimating habit was leaving $18,000–$22,000 a month of cost unrecovered — every month, on schedule, like a bill she was paying herself.
Leak Three: The Reliable Accounts Were the Worst Ones
Her two most dependable commercial accounts — flat per-square-foot rates negotiated two years earlier — contributed about 14% gross margin. The residential work she sometimes turned away to protect commercial capacity ran 35–42%. She was prioritizing her worst-margin work because it was her most predictable work. Busy and broke is usually this, underneath: the calendar full of the wrong jobs.
Leak Four: Growth with No Bridge
Commercial payment cycles ran 60–70 days. She was floating $180,000–$220,000 of completed, unpaid work at any moment with no line of credit at all. Growth had outrun her working capital, and the gap was being bridged by her personal savings — the most expensive and least sustainable financing in the industry.
What the Next Months Looked Like
Pricing rebuilt from cost up. Containment allowances reset by room count and square footage. Both commercial accounts repriced — one accepted on the spot; the other pushed back, then accepted when she held her floor. A $250,000 revolving line of credit put a real bridge under the payment cycle. Revenue ended up similar. Gross margin moved from 29% to 41%. Her personal savings haven’t been touched since.
Well-executed mold remediation should return 45–60% gross margin. Below 35%, the problem is pricing or cost control — and it is findable. The complete case file is The Profit Detective Files: The Mold Company That Was Busy and Broke.
Related reading
- The Mold Company That Was Busy and Broke
- What I Found in a $2.3M Alberta Restoration Company With No Cash
- The Franchise Owner Who Didn’t Know What His Company Was Worth
Mike McCabe is The Profit Detective — a Master Cleaner, Master Restorer, and 36-year restoration business veteran.